

Instant Cash Advance: Loan App
by Smart Finance Club
4.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.0
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
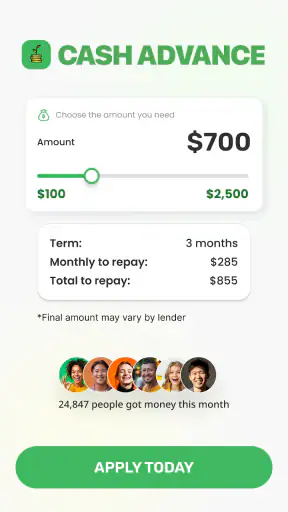
 Analysis by Getfullapps
When money is tight, the hardest part is often not finding a financial app but understanding what will happen after you open it. Instant Cash Advance: Loan App is aimed at people who need to explore a short-term cash advance through a simple mobile process. I approached it as a finance app rather than as a general budgeting tool, and that distinction matters: its purpose is immediate borrowing, not long-term money management.
The app is free to download, has an Everyone age rating, and comes from Smart Finance Club. It has built a modest user base, with over one hundred thousand installs and an average rating of four stars from around three thousand ratings. Those figures suggest that plenty of people find the basic experience useful, while the rating also leaves room for a careful look at the parts that may feel less comfortable or less clear.
How the borrowing journey feels to use
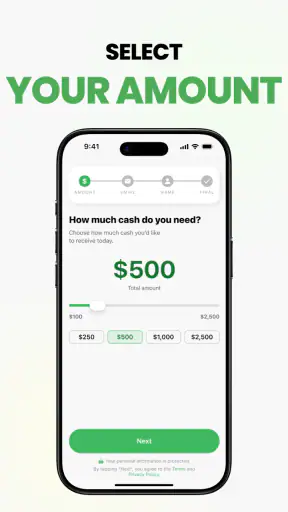
I found that a short, three-step borrowing journey is most useful when I treat it as a way to organize a decision, not as a reason to hurry. Before opening the app, I would identify the smallest amount that addresses the immediate bill and decide what repayment would realistically leave available for essentials. That preparation makes it easier to judge each screen on its own terms, which leads to the more important question of whether this route fits the situation at all.
Readable navigation for a stressful task
My first impression is that the app’s main value is its directness. It presents itself around a cash advance rather than surrounding the user with unrelated financial tools. That focus can be helpful when someone is trying to complete a task quickly, especially on a phone where excessive menus make financial forms feel more intimidating.
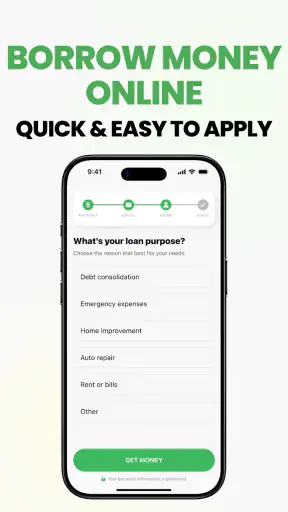
The advertised journey is built around three steps. That sounds manageable, but a short process should not be confused with a simple financial decision. I would still slow down at every screen that asks for personal, employment, banking, or repayment information. A compact application flow can reduce navigation effort while making each piece of text more important, because a user may have less time to notice an explanation before moving forward.
For readability, I found the most useful approach was to treat every label, notice, and repayment-related detail as something to read rather than skim. This is particularly important for people who use larger text, screen magnification, or a slower reading pace. If a screen is dense, increasing the device’s text size may make the content easier to follow, although enlarged text can sometimes cause buttons or lines to wrap differently in any mobile app.
I also recommend keeping the phone in a quiet place and completing the process in one sitting when possible. Switching between apps to search for account details or income information can make it easier to lose track of what a field is asking. Before beginning, I would gather the information I expect to need and make sure the device has enough battery and a stable connection.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A useful habit is to pause before submitting each stage and repeat the key details in my own words: how much I am requesting, what repayment would involve, and whether the information belongs to me. This is not a feature of the application, but it is an effective way to reduce mistakes in a fast financial workflow.
Motor and sensory considerations
People with limited dexterity may appreciate a short flow because fewer screens can mean fewer taps, swipes, and chances to lose their place. However, short does not automatically mean accessible. A user with tremors, reduced precision, or fatigue still needs comfortably sized controls and enough time to review a field before moving on. I would not rush through the process simply because the app describes it as fast.
For users with visual impairments, the practical experience will depend heavily on how the phone’s own accessibility tools interact with the app. Larger system text, display zoom, high-contrast settings, and a screen reader can help, but I would test the opening screens before entering sensitive information. If a label is not announced clearly, a button is difficult to locate, or an important notice becomes confusing after zooming, that is a serious barrier in a lending context.
Users with hearing loss are less likely to be affected by spoken instructions if the essential information appears in text. I would still avoid relying on notifications or audio prompts alone. Anyone who is sensitive to motion, flashing, or visual clutter may find a focused finance screen easier than a busy financial dashboard, but the safest assumption is to use the app in a calm display mode and stop if the presentation becomes uncomfortable.
For people with cognitive disabilities, attention difficulties, or anxiety around borrowing, the three-step structure can provide a useful sense of order. The trade-off is that a quick sequence may encourage impulsive decisions. I would write down the amount needed and the date by which repayment would be realistic before opening the app. That small preparation turns the process from a hurried reaction into a more deliberate choice.
Using the app in everyday situations
Imagine a user discovers that a necessary household payment is due before payday. They have a phone, a few quiet minutes, and enough information to complete a request, but they are already stressed. This is the kind of situation in which the app’s narrow purpose can be helpful: it offers a mobile route to investigate a cash advance without requiring a visit to a branch.
Even in that scenario, I would not treat speed as the main measure of success. The better workflow is to first calculate the smallest amount that solves the immediate problem, then compare that amount with the repayment date and the user’s next available income. If the repayment would create another shortfall, the app is probably not solving the underlying issue; it is moving the pressure forward.
The app may also suit someone who finds traditional financial websites difficult to navigate. A phone-based process can be more comfortable for users who rely on touch interaction, who have limited transportation, or who need to complete a task outside normal office hours. That convenience is meaningful, but it should not replace careful reading or comparison with other options.
For users with limited data access, an interrupted connection could be frustrating during a form. I would avoid starting the application while travelling through an area with unreliable service. Someone who shares a phone should also think about privacy before entering financial information, including whether other people can access the device, notifications, or browser history.
What the app does well for different users
The strongest inclusive quality here is focus. This is not presented as a complicated investment platform or a multi-purpose banking suite. A person who only wants to explore a cash advance may find a dedicated route easier to understand than a large app filled with charts, account categories, and unrelated promotions.
The free installation also lowers the initial barrier to trying the service. That does not mean borrowing is cost-free, and I would never interpret a free app as a free loan. The important distinction is between downloading the application and accepting any financial offer shown inside it. I would look carefully at the full repayment obligation before agreeing to anything.
The Everyone rating makes the app broadly suitable for general audiences from a content-classification perspective, but a borrowing decision is still an adult financial responsibility. Younger users should not assume that an age label means they can independently qualify for or safely use every financial service shown in the app.
The current version is 2.0.7, and the app supports devices running Android 7.0 or later. That broad device coverage is useful for people who keep an older phone because replacing it is expensive or because newer interfaces are difficult to adjust to. At the same time, older hardware may respond more slowly, and users should allow extra time rather than repeatedly tapping a control that seems delayed.
Where the experience still needs caution
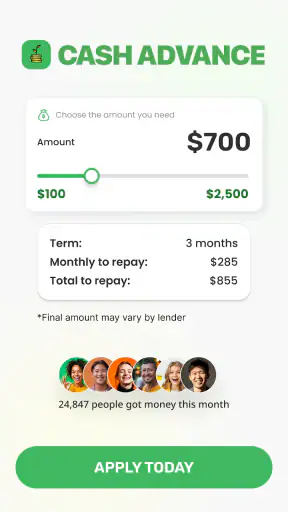
The biggest barrier is financial comprehension, not navigation. A user may be able to complete three steps and still misunderstand the total amount they will repay. I would treat any figure connected with fees, timing, or repayment as more important than the app’s promise of speed. If an explanation feels vague, the right response is to pause, not to guess.
Another limitation is that a focused cash-advance app cannot replace a full view of personal finances. It is not the right first choice for someone who wants spending categories, bill reminders, savings goals, or a long-term debt plan. A budgeting app, a credit union conversation, an employer advance program, or a direct discussion with a bill provider may be more suitable depending on the situation.
I would also avoid using it as a routine bridge between paydays. Repeated short-term borrowing can hide a recurring gap in income and expenses. The app may be useful for investigating a one-off need, but it is a poor substitute for building an emergency reserve or renegotiating an unaffordable bill.
There is a practical accessibility issue in any app that asks for sensitive information: users may need help from a trusted person. That can be appropriate, but assistance should not mean handing over passwords or allowing someone else to make the decision. A safer arrangement is for the helper to read instructions aloud, explain screen controls, or assist with device settings while the account holder enters and reviews their own information.
People who cannot comfortably read small text, who have difficulty with touch accuracy, or who become overwhelmed by financial forms should test the early interaction before committing time. If the phone’s accessibility features make the screen harder to interpret, a larger device or a supported desktop alternative may be better. I would not recommend continuing simply because the process has already started.
How it compares with familiar alternatives
Compared with visiting a bank or credit union, a mobile cash-advance application is more convenient and less dependent on travel or opening hours. A face-to-face conversation can be better, however, for someone who needs a repayment explanation in plain language or wants to discuss several financial options rather than one immediate request.
Compared with a general budgeting app, this product is more targeted but much narrower. A budgeting tool helps identify why money is short and may support planning before a crisis. Instant Cash Advance: Loan App is more relevant when the user is already considering short-term borrowing and wants a phone-based route to explore it.
Compared with asking a bill provider for an extension or payment plan, borrowing through an app may feel faster but can add another obligation. I would always compare the two paths. A payment arrangement may solve the immediate timing problem without creating a separate repayment commitment, while a cash advance could be more suitable only when the user understands the complete cost and has a dependable way to repay.
Compared with informal borrowing from family or friends, an app may feel more private and less emotionally difficult. The trade-off is that formal financial obligations require especially careful attention to terms. Privacy and convenience are valuable, but neither should outweigh clarity.
Who should consider it and who should skip it
I can see the appeal for a user who needs to research a short-term cash advance from a phone, prefers a concentrated three-step flow, and can read and verify financial information independently. It may also help someone who cannot easily travel to a financial office or who prefers completing an initial request digitally.
I would suggest skipping it if the user is unsure how repayment would fit into the next pay cycle, is already juggling several short-term debts, or is looking for a complete money-management system. It is also not a good match for someone who expects the word “instant” to mean guaranteed approval, immediate funds in every situation, or no financial cost. Those are assumptions I would avoid.
Before using it, I would prepare a short checklist: the exact amount needed, the reason for borrowing, the next realistic repayment date, and an alternative if the request is unsuitable. I would also keep a record of any offer or agreement for personal reference. This workflow is especially helpful for users who have memory difficulties or who become distracted during forms.
My inclusive verdict after using the app
Instant Cash Advance: Loan App is a focused finance app from Smart Finance Club that makes sense for people exploring short-term borrowing through a phone. Its simple three-step idea, free installation, Everyone rating, and support for Android devices from version 7.0 make it approachable in several everyday contexts, particularly for users who value a direct mobile route.
My recommendation comes with a firm condition: use the app as a way to examine an option, not as a reason to borrow quickly. The clearest experience will belong to users who can adjust their device for comfortable reading, take their time with each screen, and calculate repayment before submitting anything. People who need broader financial guidance, repeated help with debt, or a more personal explanation may be better served by a budgeting tool, a credit union, or a conversation with the bill provider.
With around three thousand ratings and more than one hundred thousand installs, the app has enough public use to show that it is not an obscure experiment, while its four-star average suggests a generally positive but not flawless reception. I see it as a practical, narrow tool rather than a complete financial solution. The most important accessibility feature is still the user’s ability to understand the obligation before accepting it.
In short, I would recommend trying Instant Cash Advance: Loan App only when the need is specific, the repayment plan is realistic, and the interface remains comfortable with the user’s accessibility settings. If any of those conditions fail, slowing down or choosing a different financial route is the more responsible decision.
Pros
- Easy to use interface for quick navigation.
- Fast approval process for urgent needs.
- No credit check required for loan eligibility.
- Flexible repayment options available.
- Secure data encryption ensures privacy.
Cons
- High-interest rates compared to traditional banks.
- Limited loan amount options.
- May charge additional fees for late payments.
- Requires access to personal information.
- Not available in all regions.
FAQs for Instant Cash Advance: Loan App
What is Instant Cash Advance: Loan App and how does it work?
Instant Cash Advance: Loan App is a mobile application designed to provide quick and easy payday loans to users in need of immediate financial assistance. Once you download the app, you can apply for a loan by following a simple application process. The app evaluates your eligibility based on your income and employment status to offer a suitable loan amount.
Is Instant Cash Advance: Loan App safe to use?
Yes, Instant Cash Advance: Loan App is designed with user security in mind. It employs advanced encryption technologies to protect your personal and financial information. It is crucial, however, to ensure you download the app from reputable sources like the Google Play Store or Apple App Store to avoid counterfeit versions.
What are the eligibility requirements for a loan?
To be eligible for a loan from Instant Cash Advance: Loan App, you typically need to be over 18, have a stable income source, and a valid checking account. Some additional requirements may include a minimum credit score and proof of identity. The app will guide you through the exact requirements during the application process.
How quickly can I receive the loan funds?
Once your loan application is approved, Instant Cash Advance: Loan App usually disburses funds within a few hours to a day. The speed of receiving funds depends on your bank's processing times. The app is designed to provide rapid access to cash, making it suitable for urgent financial needs.
Are there any fees or interest rates associated with the loans?
Yes, Instant Cash Advance: Loan App charges interest and may have additional fees associated with the loans. The interest rates and fees depend on the loan amount and your creditworthiness. It's important to review the terms and conditions thoroughly before accepting a loan to understand the total repayment amount.











